This is a preview from our last October Macro Snapshot (Published Oct 1).
Find out more here.

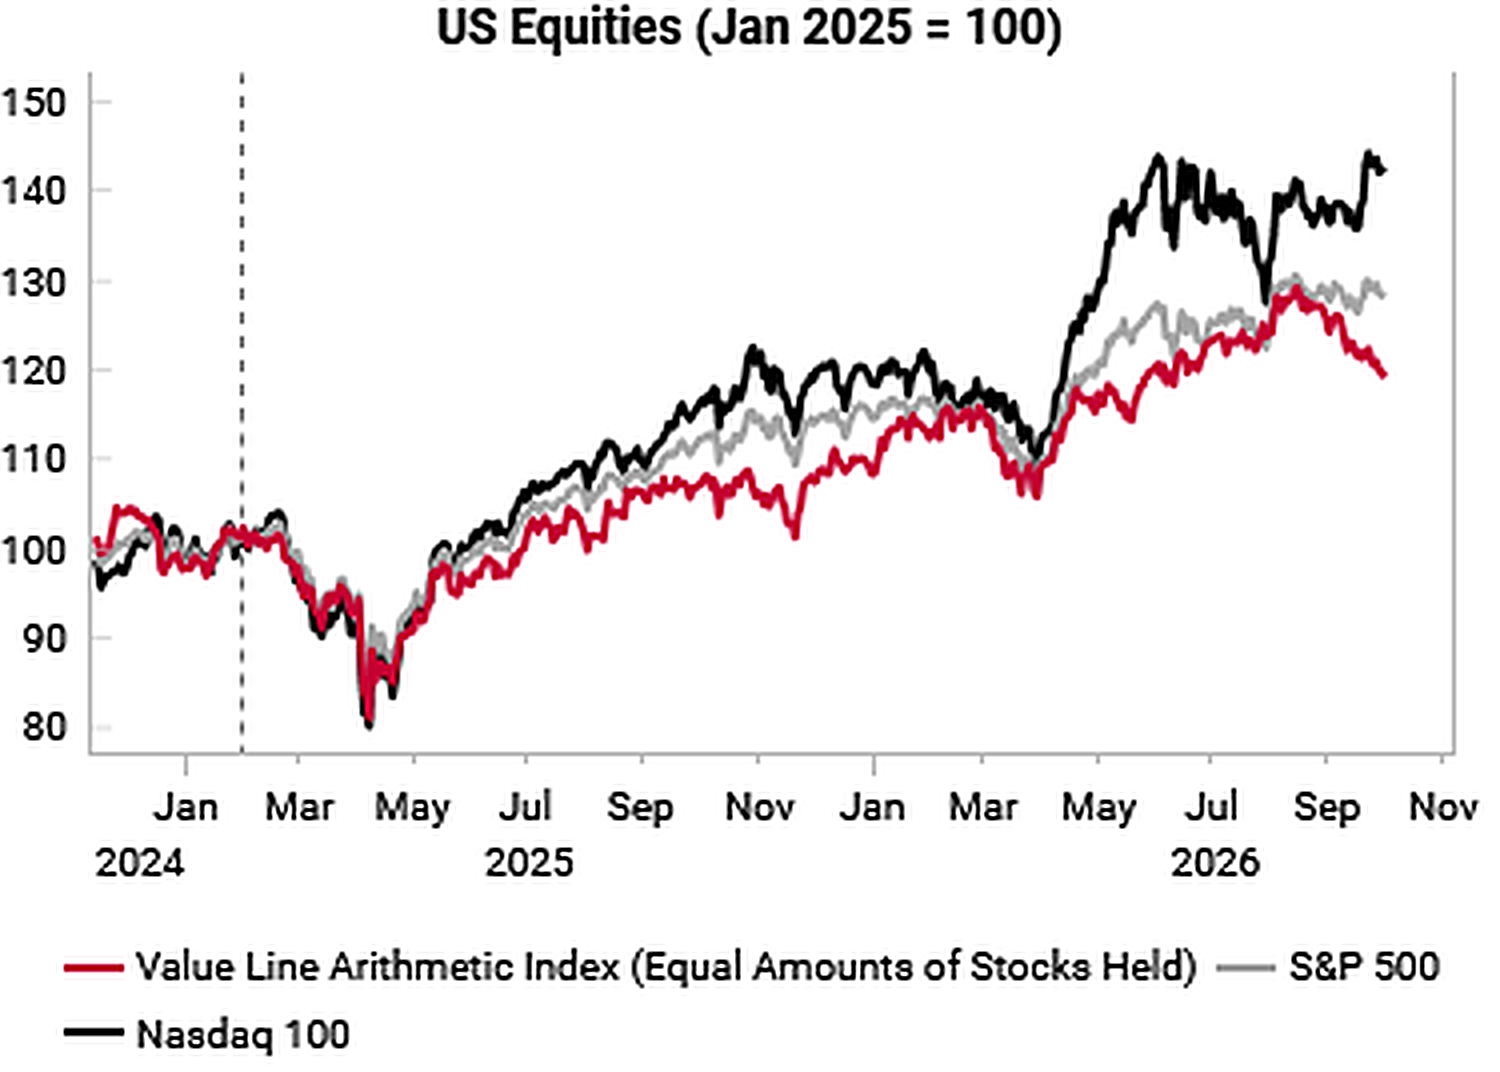
Equity breadth is starting to weaken after the Fed’s first hike.
The equal-weighted Value Line Arithmetic index is drawing down from its August high, while the Nasdaq 100 is rallying.
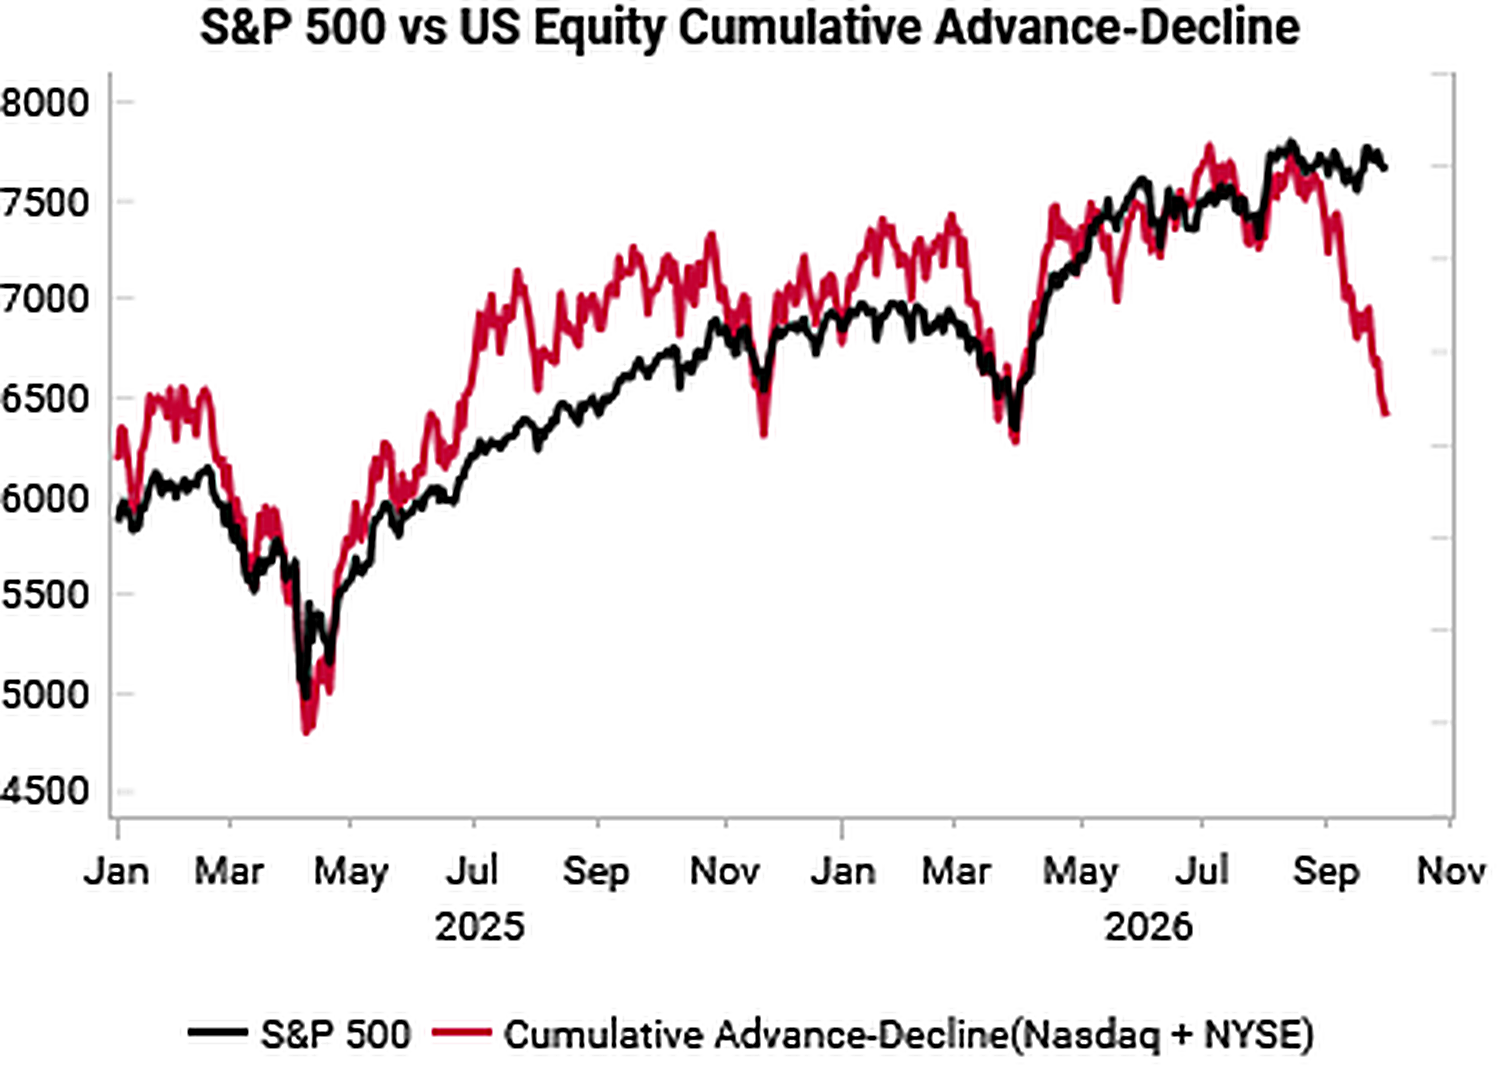
The cumulative advance-decline line has also dropped back to its spring lows, even as the S&P 500 holds near the highs.
That means more stocks are falling than rising, even if the index is up.
In our 2025 report, Lessons for today from the 1929, Nifty Fifty and Dotcom bubbles, we laid out that narrowing leadership alongside monetary tightening is the classic combination seen ahead of generational equity tops.
Today is the first time in this cycle we are seeing both.
Market tops are a process, not a single event.
Being too early can work out the same as being wrong.
We flag again our “Juniper Networks” analog.
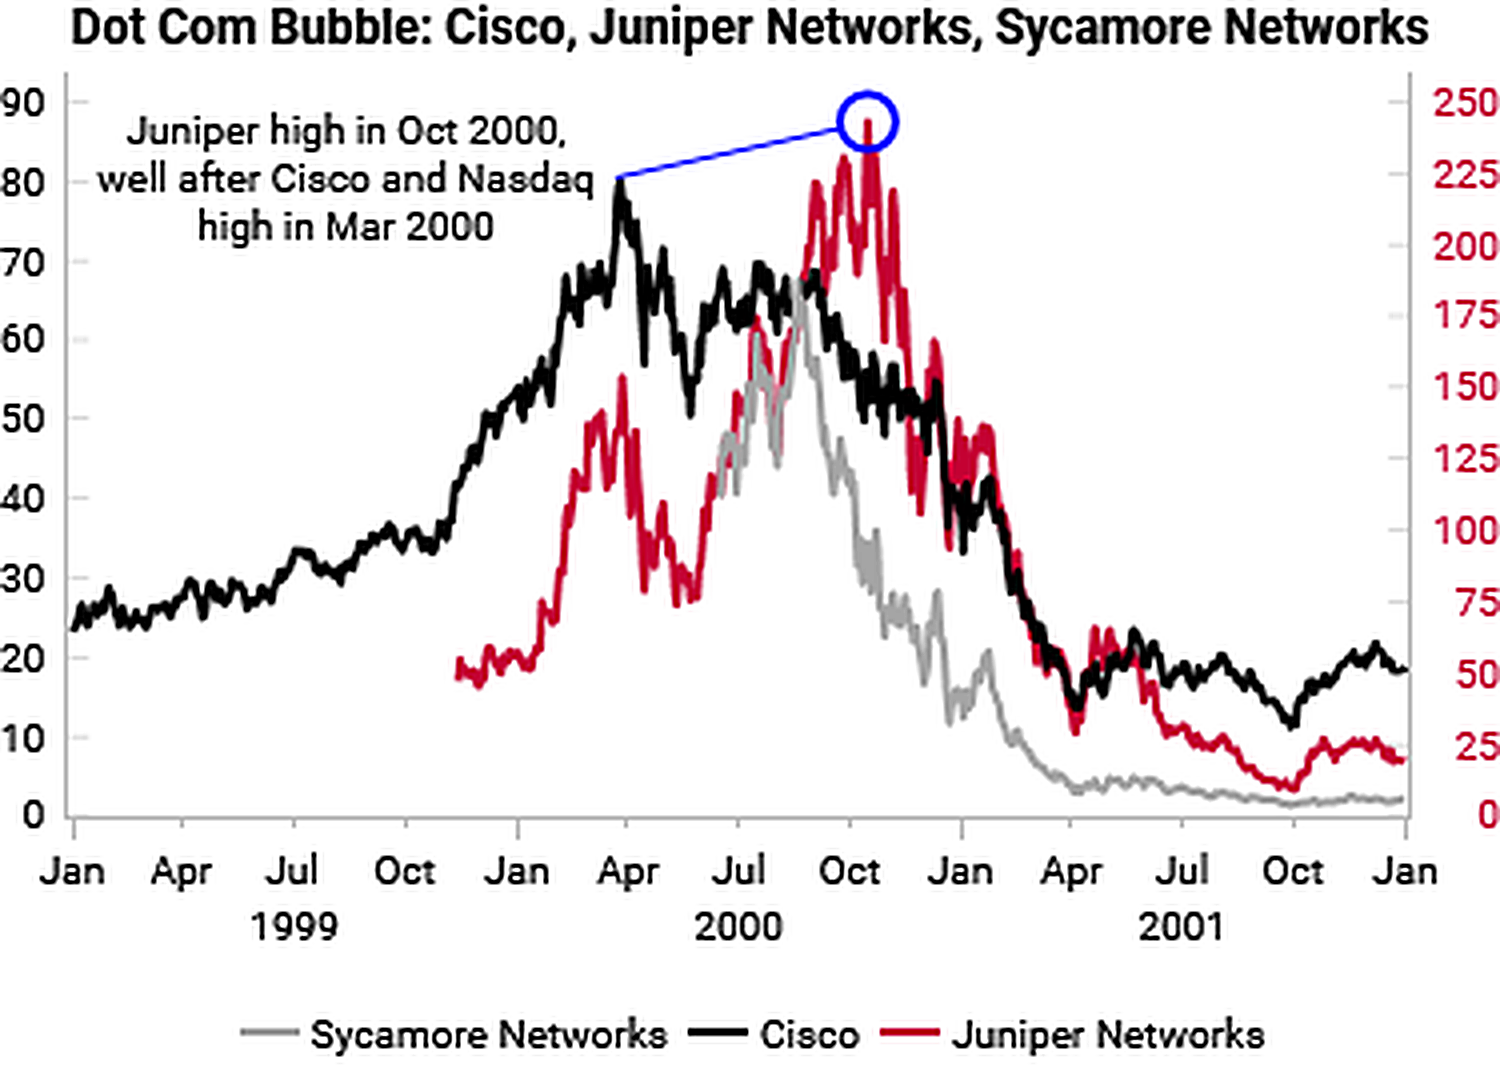
In the dot-com era, Cisco peaked in March 2000, but Juniper Networks went on to make its high in October 2000 as the late-stage IPOs soaked up liquidity from previous leaders.
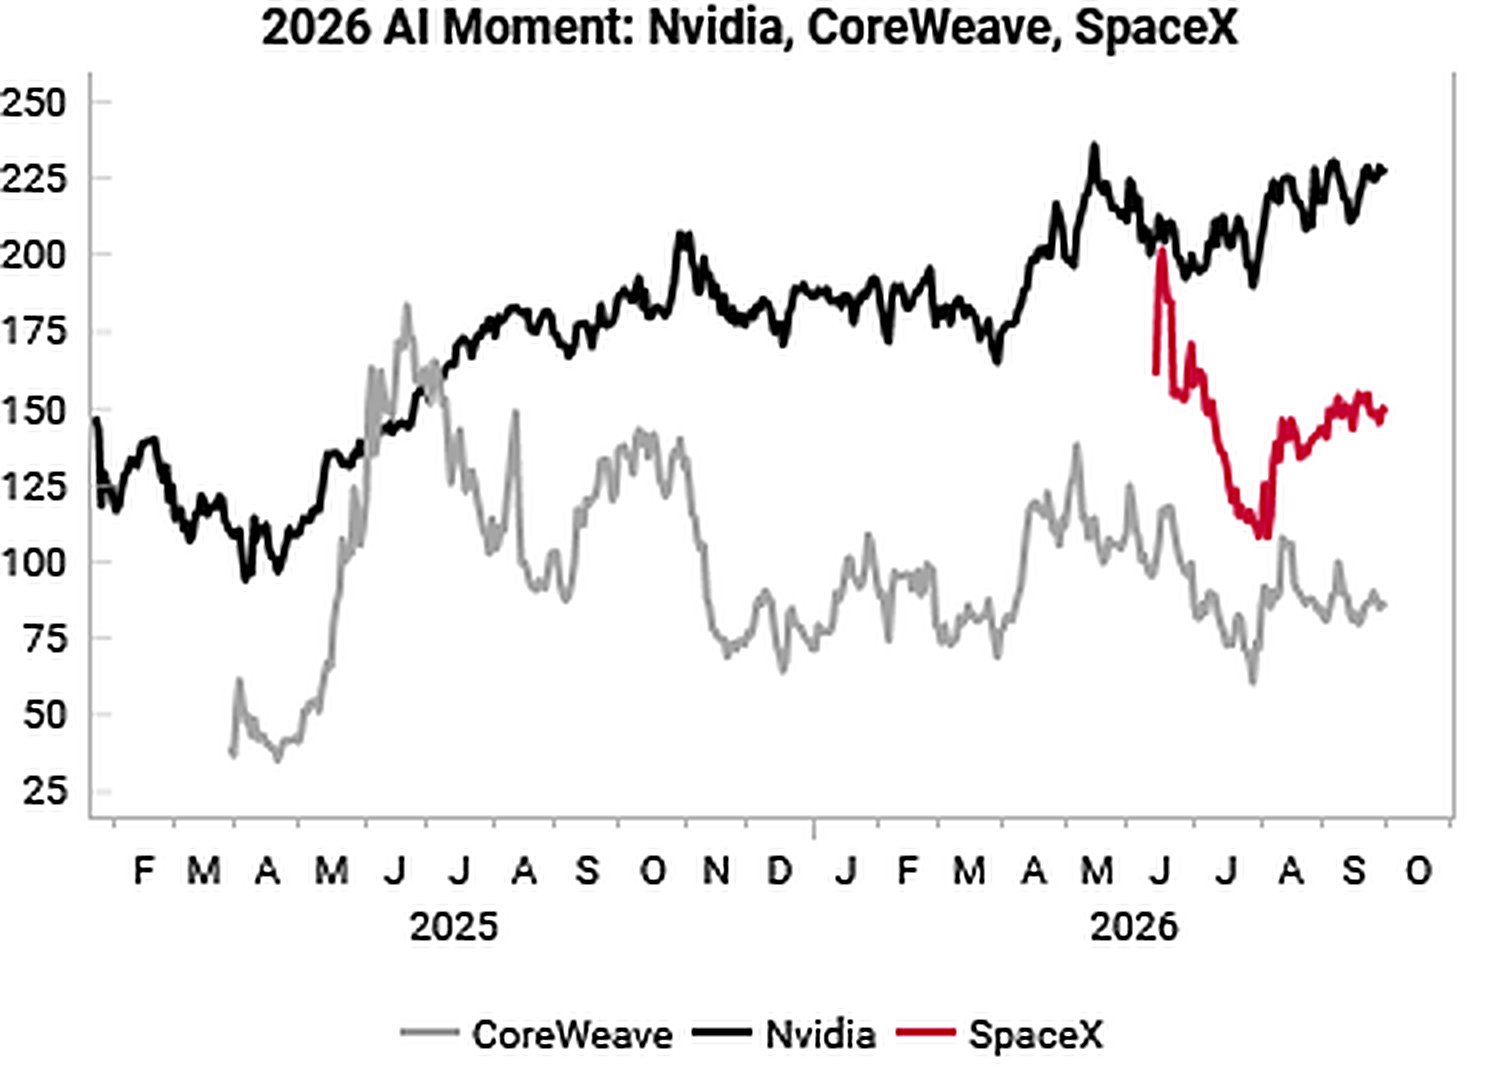
Today, Nvidia is holding up while the second-tier names have already drawn down.
CoreWeave is around half its 2025 high and SpaceX is about 25% below its post-IPO peak.
With Anthropic and OpenAI delaying their IPO dates, there are increasing signs that the public equity market is running out of marginal buyers.
Asset Allocation Engine

ETFs vs 60/40