This is a preview from our last October EM/DM Leading Indicator Watch (Published Oct 26).
Trial our work here.

Lula’s shock win has triggered a sharp drawdown in Brazilian assets. Our previous election research says this is usually a buying opportunity.
In our previous thematic report, When election risks matter for investors, we showed that the high risk premia associated with contentious LatAm elections tend to unwind over the following year after the results, no matter who wins.
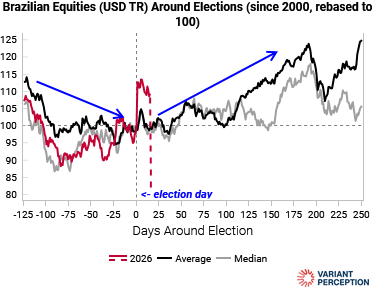
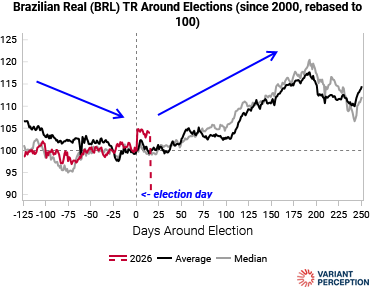
Lula’s first win in 2002 is the template: the real collapsed, then rallied strongly through 2003. This is because the feared policy shifts usually prove milder than priced.
Today, the Brazilian economy still looks fine.
Inflation remains moderate, leaving the real policy rate very high at almost 9%.
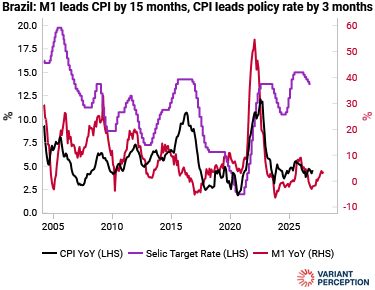
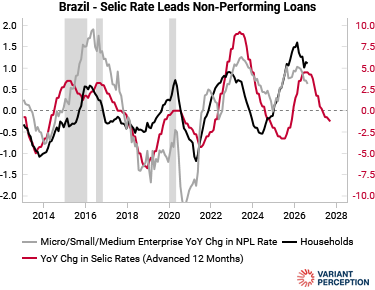
M1 growth shows no sign of an inflation surge, and past Selic cuts point to falling NPLs.
Of course, the risks are fiscal and institutional.
Expect plenty of headline risks in the coming days and weeks as Flávio Bolsonaro is contesting the result.
We would look to scale into this sell-off to accumulate long-term positions. Brazil still has one of the highest real yields in the world, offering a margin of safety that is not readily available in other asset markets.