


This is a preview from our last October G3 Leading Indicator Watch (Published Oct 6).
Receive the full report here.

Our US growth leading indicator is still trending sideways at just under 2% annualized.
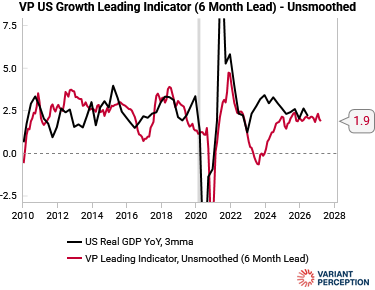
That is well below GDPNow, which reflects a bifurcated economy.
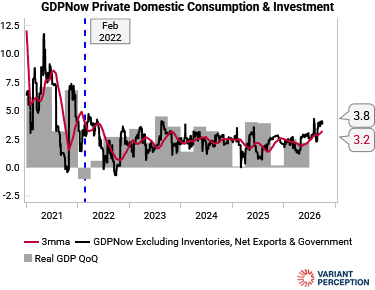
AI-linked activity is lifting headline growth, while our leading indicator is picking up the drag from rising input costs and yields.
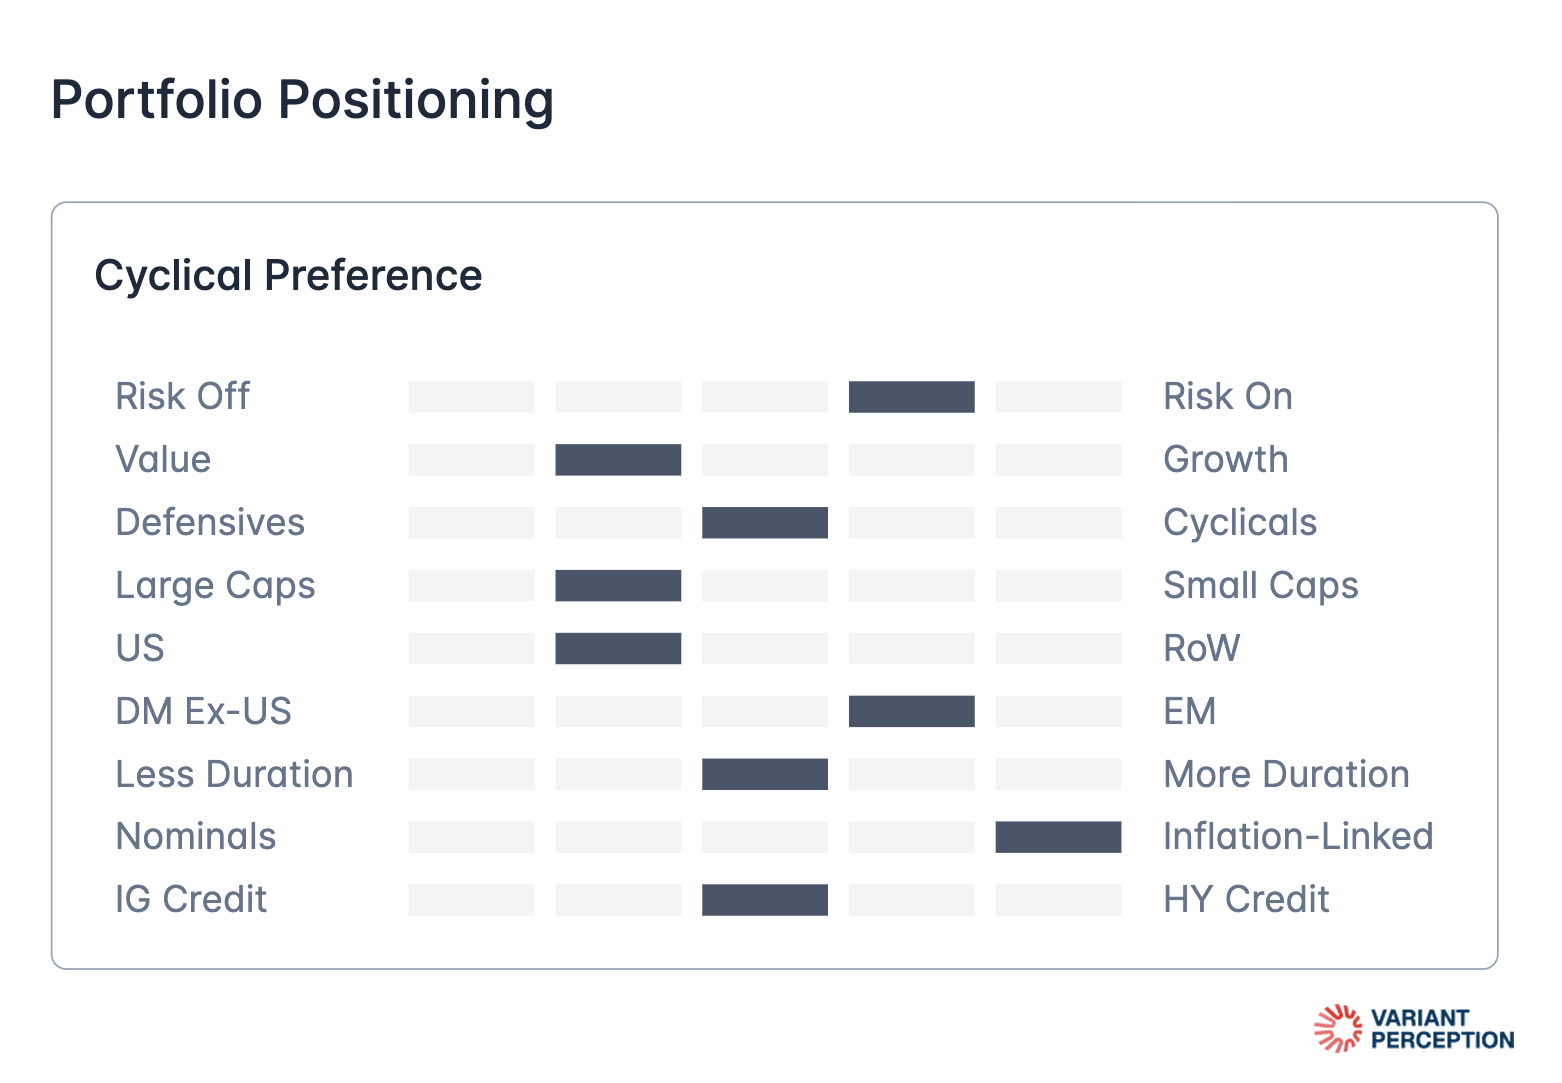
We are transitioning to a less supportive macro backdrop.
As we previously noted, the first Fed hike is usually a reaction to economic resilience and rarely leads to recession within 12–18 months.
Instead, it signals a late-cycle environment, with narrowing economic strength and narrowing market breadth.
The latest ISM surveys corroborate this.
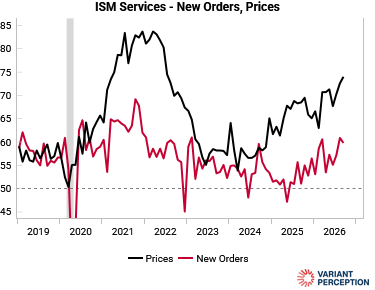
New orders remain healthy in both services and manufacturing, but they lag the rise in prices.
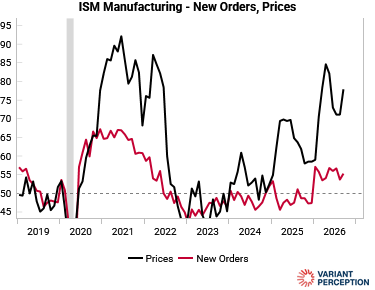
That implies slowing real volumes, though not yet a recession.
Asset Allocation Dashboard


The bifurcated economy point is doing a lot of work here, and it matches what Thursday's tape looked like. The Dow put on 550 points while the Nasdaq sat flat, money walking out of AI and into healthcare and the rest of the market. If the late-cycle call is right, the narrowing you describe is exactly what a defensives rotation looks like in its early days. The question I am left with: when economic strength narrows to a few AI-linked names, does the first hike expose that narrowness, or does the resilience of the AI capex cycle delay it?