This is a preview from our November G3 Leading Indicator Watch (Published Nov 16).
Try our work here.
The primacy of sovereignty strikes again! Check out our Odd lots episode with Joe Weisenthal and Tracy Alloway.


Global: Growth momentum weakening, falling excess liquidity points to flatter curves
(Nov 16, 2026)
We remain in a late-cycle regime, where policy stays restrictive while growth slows. Our US growth LEI is still steady, while China’s remains weak and the Eurozone’s is deteriorating.
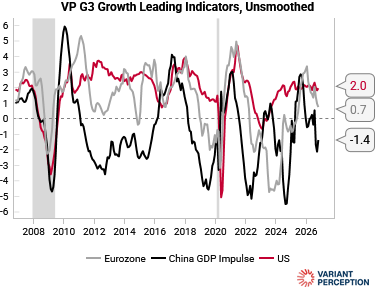
Globally, the majority of the inputs into our growth LEIs are worsening QoQ.
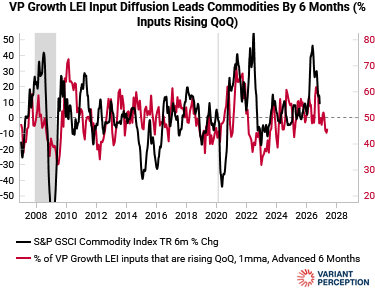
A Fed that keeps hiking will accelerate late-cycle dynamics.
Inflation surprises have turned positive, and markets are pricing 27bp of hikes for December and about 80bp by June 2027.
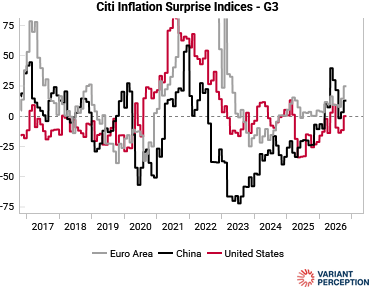
Consensus sees the Fed hiking into strong growth; we see it hiking into slowing growth, which risks inverting the curve.
A flattening and inverting yield curve would be consistent with the falling excess liquidity we are seeing at present. Global excess liquidity leads the 5s30s curve by six months, and it has rolled over.
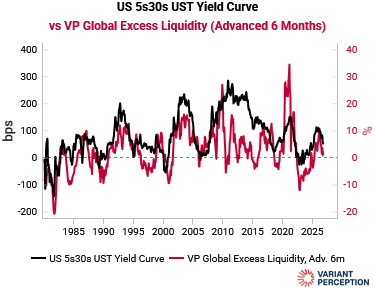
We are concerned that policy won’t be able to get ahead of a slowdown.
The midterm defeat has fractured the Trump administration, and the Fed is split, from Waller floating 50bp to Williams seeing no overheating.
Our Macro Risk Indicator is still rolling over (link), seeing only a 50% chance that equities outperform bonds over the next six months.