This week's charts and research highlights from Variant Perception.
REVISITING OUR TOP 10 SURPRISES FOR 2026 - WEBINAR
with Tian Yang
Fund Manager of VPX ETF
&
CIO of Variant Perception
—
Sep 24, 2026 03:00 PM (BST)
Top 10 Surprises for 2026
(Dec 2025)
Trump’s capex boom arrives a year late, broadens beyond AI
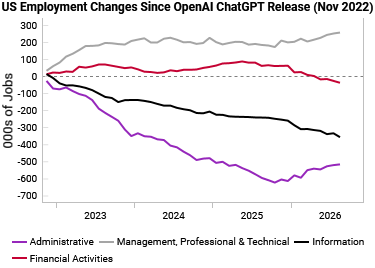
US growth surprises to the upside despite muted labor market
Housing disinflation breaks sticky inflation narratives
US 10y yields go nowhere, trades in a tight range around 4%
Value equities outperform growth
G10 FX divergence: Apac (AUD & NZD) over Europe (EUR & GBP).
EM equities outperform DM, led by Brazil
Oil trades below 50 and above 75 at some point during the year
China tech stocks outperform US tech stocks
Capital Cycle: US regional banks & energy services outperform
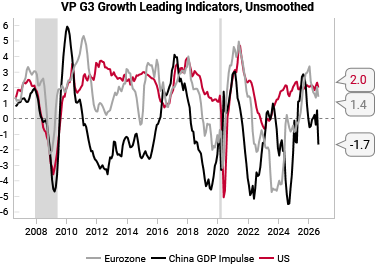
Growth softer, tails wider - Sep. G3 Leading Indicator Watch
(Sep 10)
Steady US growth outlook with balanced risks. Renewed services PMI strength is the upside surprise to watch. Consumer still weak as real incomes flatten and the savings rate turns up.
US Core inflation trends remain muted, but Iran and El Niño keep the energy and food tails outside policymakers’ control.
In a reversal of last month’s improvement, China growth LEI fell. Domestic demand are weak, but not yet near conditions before Oct 2024 policy pivot. We stay long EURCNH.
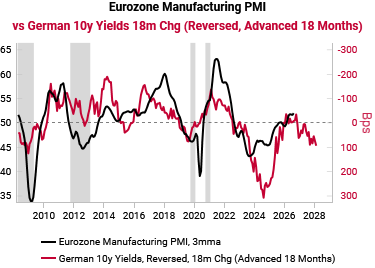
Our Eurozone growth LEI gave back last month’s improvement. Energy costs and lagged yield rises bite. Sticky services inflation and abnormally low gas storage keep stagflationary tail risks alive into winter.
DM
UK: Growth headwinds + fading inflation impulse => Stay long SONIA Futures (SFIZ7)
Japan: Impossible trinity still not resolved, expect more JPY policy actions
Australia: Housing headwinds + negative real wage growth => look to fade rise in 2y yields
Sweden: Positive outlier as growth LEI remains very strong, retain bullish SEK bias
EM
Brazil: Growth leading indicators remain resilient, waiting for October elections to pass
S. Korea: Economy remains K-shaped, as semi boom has yet to trickle down
India: RBI regime model remains hawkish, El Niño food inflation risks remain
Indonesia: From extremely hated to less hated, take profits on equity
Trial our Research?