This is a preview from our November Macro Snapshort (Published Nov 2).
Try our work here.
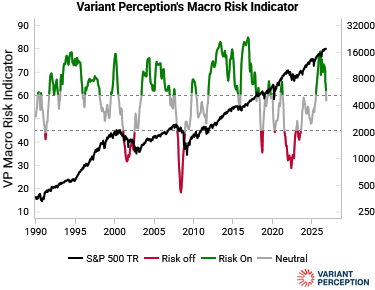
Our Macro Risk Indicator has slipped from the “Risk-On” regime to neutral, continuing its multi-month downtrend.
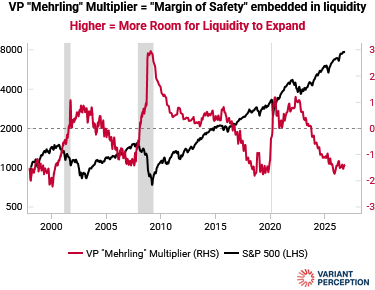
The policy and liquidity components are now rolling over too.
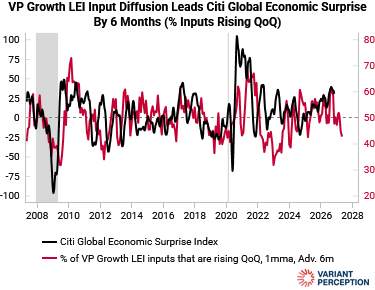
This is a typical late-cycle dynamic: growth and inflation are set to decelerate, policy is turning restrictive, and liquidity is running out of room to expand.
This year’s drop from “very bullish” to neutral has five precedents:
2000,
2007,
2010,
2015, and
2018.
They are not all the same.
What separated the major tops in 2000 and 2007 from the short-lived drawdowns of the 2010s was the level of inflation, which constrains central banks.
In the 2010s, inflation was consistently low, so central banks pivoted quickly and reflated markets before the downturns built momentum. In 2000 and 2007, by the time policymakers eased, it was too late. Today, headline CPI is 3.7% and the Fed is still hiking.
Cyclically, we recommend investors de-risk towards a more balanced allocation: reduce equities, add fixed income or cash.
Neutral is not yet “risk-off”, but the macro headwinds are building.